
HBM semiconductor equipment stocks: TOWA orders jump 125.8%, Wonik IPS revenue to near double
Expansion of high bandwidth memory capacity is feeding orders at chip equipment makers such as TOWA and Wonik IPS. Earnings beats sit alongside a profit miss at SK Hynix, a reminder of the risks.
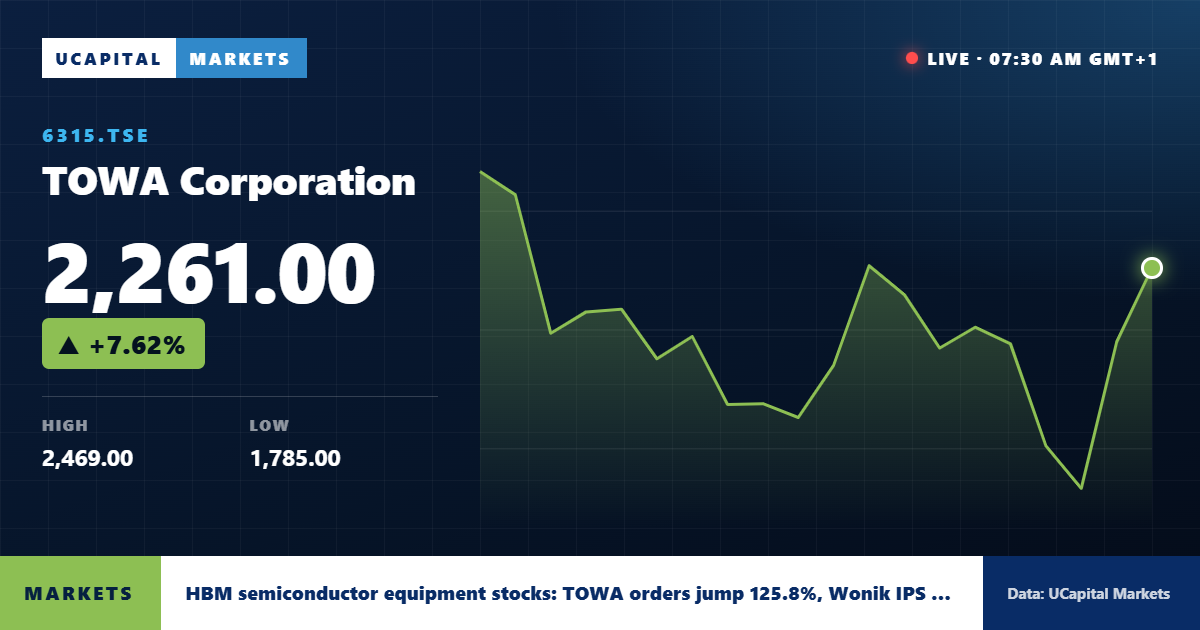
- 01TOWA (6315.TSE) quarterly orders rose 125.8%, according to the brief's figures, as HBM capacity expands.
- 02Wonik IPS (240810.KQ) reported on 9 November earnings per share of 1,848 against an estimate of 496.88.
- 03Wonik IPS revenue is set to nearly double between 2025 and 2027.
- 04SK Hynix (000660.KO) reported on 27 October revenue of 104,615.5 billion in reporting currency, above the 98,202.65 billion estimate, but EPS below forecasts.
TOWA Corporation (6315.TSE) has seen quarterly orders rise 125.8% as memory makers expand capacity for High Bandwidth Memory, while Wonik IPS (240810.KQ) is set to nearly double revenue between 2025 and 2027. The figures put HBM semiconductor equipment stocks at the centre of the AI hardware debate.
The question for investors is which suppliers actually capture the spending and how much of it is already in valuations. The latest reported numbers from TOWA, Wonik IPS and SK Hynix (000660.KO) give a partial answer, and they also show where the risks lie.
What happened
TOWA, the Japanese maker of chip-packaging equipment, recorded quarterly orders up 125.8%, a surge tied to the build-out of HBM production lines. The company is also reported to be eyeing its biggest-ever order for chipmaking machines from South Korea, where the leading HBM producers are based.
In its latest reported quarter, TOWA posted earnings per share of 28.99 against an estimate of 24, and revenue of 17.53 billion in reporting currency against an estimate of 16.68 billion. That is a beat of roughly 21% on earnings per share and 5% on revenue.
Wonik IPS, a South Korean supplier of semiconductor process equipment, reported on 9 November earnings per share of 1,848 against an estimate of 496.88. The scale of that gap is large, and the brief points to revenue nearly doubling between 2025 and 2027 as capacity additions flow through.
Key figures at a glance
- TOWA: quarterly orders +125.8%; EPS 28.99 vs 24 estimate; revenue 17.53 billion vs 16.68 billion estimate.
- Wonik IPS: EPS 1,848 vs 496.88 estimate, reported on 9 November; revenue seen nearly doubling between 2025 and 2027.
- SK Hynix: revenue 104,615.5 billion vs 98,202.65 billion estimate, reported on 27 October; EPS 54,454.3 vs 85,416.76 estimate.
How are the stocks valued?
TOWA trades at a trailing price-to-earnings ratio of 25.02 and a forward ratio of 20.02, according to the latest market data. The lower forward multiple implies that earnings are expected to grow from the trailing level.
Wonik IPS carries a trailing multiple of 18.96 and a forward multiple of 15.27. Both equipment makers therefore trade at multiples that are moderate for a group tied to an AI-driven capital spending cycle.
SK Hynix, the memory producer whose spending drives orders for such equipment, shows a trailing multiple of 4.29 and a forward multiple of 2.52. Such low readings reflect earnings that have swelled during the current memory upcycle, and they show how differently the market prices memory makers and their suppliers.
Which companies benefit from HBM expansion?
The beneficiaries are the equipment suppliers that sit between memory makers' capital spending plans and the physical production lines. TOWA supplies packaging-related machinery, and Wonik IPS supplies process tools, so both are exposed to the same underlying driver: more HBM output.
The customers matter as much as the suppliers. SK Hynix is a leading HBM producer, and Samsung Electronics (005930.KO) and Micron Technology (MU) are the other major memory makers whose capacity decisions shape orders across the industry. The data available here contain no figures for Samsung or Micron, so their spending plans are not quantified in this report.
SK Hynix reported revenue of 104,615.5 billion in reporting currency on 27 October, above the 98,202.65 billion estimate. That top-line strength supports the case for continued investment, since memory makers fund new lines from their own cash flow.
What are the risks for investors?
The main risk is that equipment orders are lumpy and follow the investment cycle of a handful of customers. A 125.8% jump in quarterly orders is a strong signal, but it also sets a high base against which later quarters will be compared.
SK Hynix illustrates a second risk. Despite beating on revenue, its earnings per share of 54,454.3 came in below the 85,416.76 estimate, showing that strong sales do not always translate into profit in line with expectations. If memory makers see margins under pressure, they could moderate capital spending, which would flow back to equipment suppliers.
Third, concentration: TOWA's prospective large South Korean order would make its results more dependent on one customer relationship. Forecasts that Wonik IPS revenue will nearly double by 2027 are projections, not reported results, and they depend on capacity plans being carried out on schedule.
Why it matters
HBM semiconductor equipment stocks matter because they translate AI demand into measurable orders and revenue well before it appears in end-product sales. TOWA's order growth and Wonik IPS's earnings beat suggest the capacity expansion is moving from planning to purchasing.
For markets, the divergence in valuation is notable. The equipment makers trade at forward multiples of 20.02 and 15.27, while the memory producer SK Hynix trades at 2.52 times forward earnings. The gap shows how investors weigh the durability of earnings differently across the chain.
The sector remains a narrow slice of the broader semiconductor stocks universe, and results vary widely between companies. This report describes reported figures and valuations; it does not rank or recommend any security.
What to watch next
The next catalysts are order disclosures and earnings from the suppliers and the memory makers they serve. Dated items named in the data are limited, so the checklist below focuses on what has been reported and what is pending.
- Confirmation of TOWA's reported pursuit of its biggest chipmaking machine order from South Korea.
- Whether TOWA sustains order growth after the 125.8% quarterly jump.
- Delivery against the projection that Wonik IPS revenue will nearly double between 2025 and 2027.
- Capital spending commentary from SK Hynix after its 27 October results, plus any updates from Samsung Electronics and Micron Technology.
- Whether SK Hynix's earnings shortfall against the 85,416.76 estimate narrows in the next reported quarter.
Sources:UCapital Markets (ucapital.com)UCapital Markets (ucapital.com)UCapital Markets (ucapital.com)asia.nikkei.com
UCapital24 S.p.A. or group companies may have commercial relationships with the companies mentioned. This content is not financial advice.
Sign up for free to ask the AI about this article.
Multiples, financials, sentiment and risks in 60 seconds, with live data.