
DSCR Mortgages Open US Real Estate Investment in Distressed Areas to More Borrowers
A loan product that underwrites on projected rental income rather than personal finances is channelling capital into long-neglected American neighbourhoods, reshaping who can access real estate investment credit.
- 01DSCR mortgages use projected rental income — not the borrower's personal wealth — as the primary underwriting criterion.
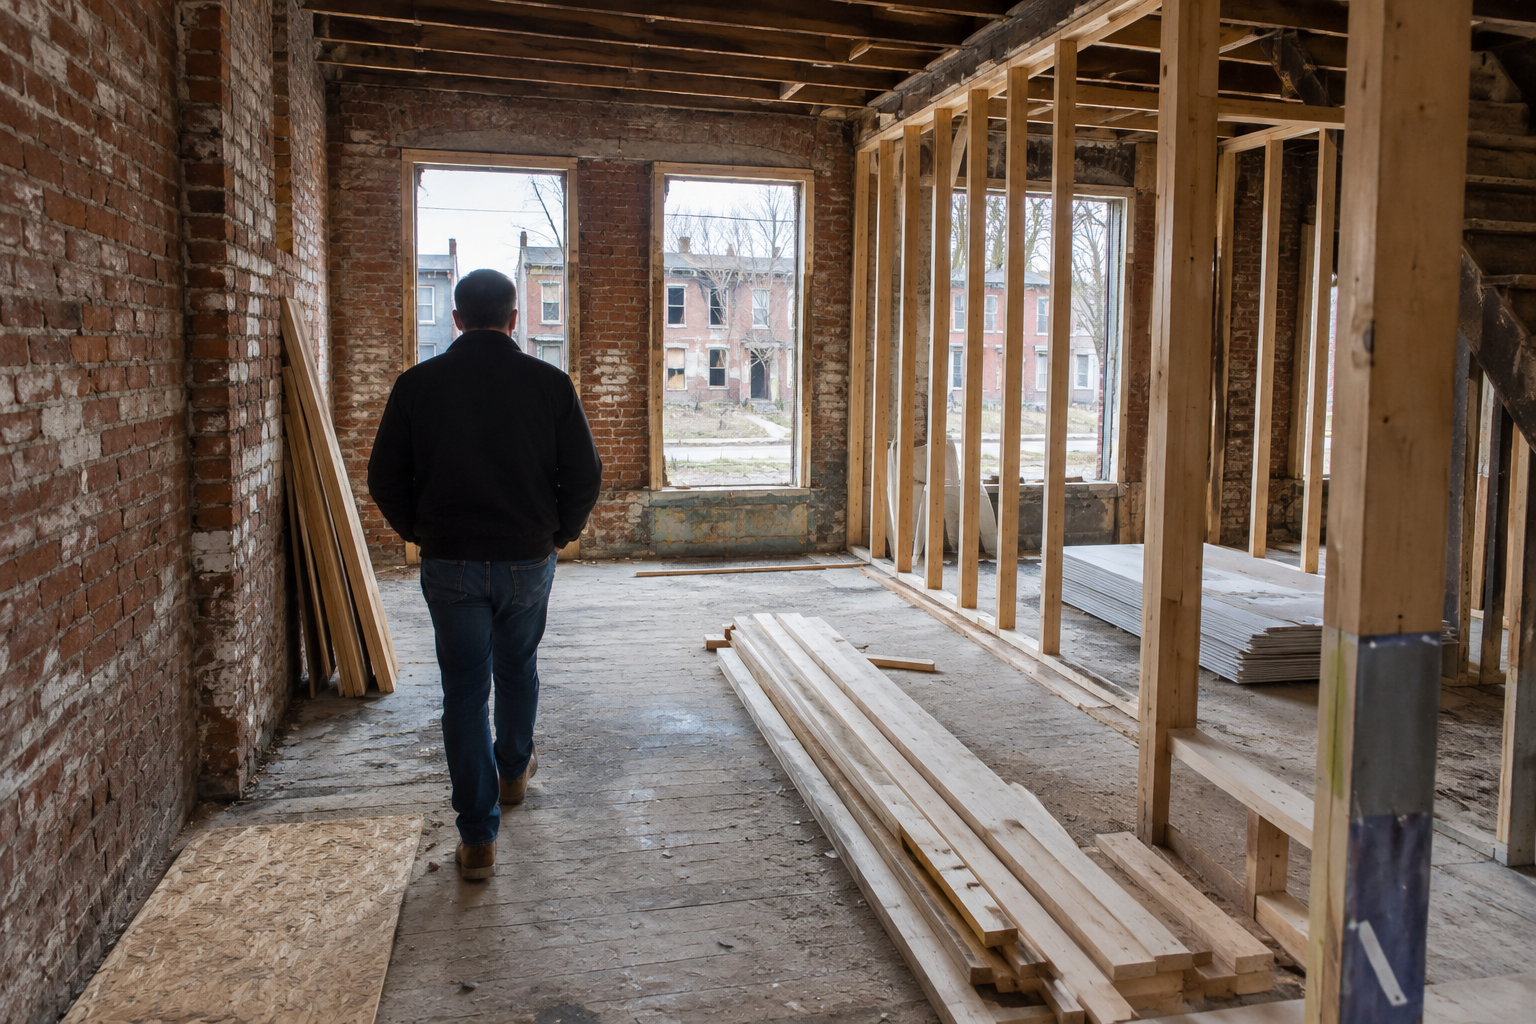
- 02East Cleveland, Ohio, redlined by the federal government in the 1930s as 'definitely declining', is among the distressed markets now attracting DSCR-backed investment.
- 03The US 30-year mortgage rate is at its highest level in over a year after rising sharply following the start of the war with Iran, according to investor sentiment data from August 2026.
A new class of United States mortgage — the Debt Service Coverage Ratio loan, or DSCR Mortgage — is directing real estate investment into some of the country's most economically distressed areas by underwriting on projected rental income rather than on the personal financial strength of the borrower, a shift that is widening access to property investment credit as of October 2026.
The product matters for US Real Estate markets because it decouples eligibility from traditional income verification, potentially unlocking capital flows into neighbourhoods that conventional lenders have avoided for decades — areas where redlining, disinvestment and persistent poverty have suppressed property values and deterred institutional money.
What happened
The DSCR Mortgage evaluates a loan application primarily on whether the rental income a property is expected to generate is sufficient to cover its debt obligations. The Debt Service Coverage Ratio itself is net operating income divided by total debt service: a ratio above 1.0 signals that projected rents exceed loan payments, making the property — rather than the borrower's salary or credit profile — the central underwriting variable.
This framework has long been used in commercial real estate lending, where cash flow from the property is generally the primary source of repayment, according to Office of Thrift Supervision examination guidance.
The application of this logic to residential investment properties in distressed communities is more recent. In East Cleveland, Ohio — a city the federal government marked as "definitely declining" in the 1930s and warned banks against lending in — DSCR-backed investors have begun acquiring and renovating homes that conventional mortgage products would not have financed, given the low appraised values and the income profiles of prospective borrowers.
What is a DSCR Mortgage and how does it work?
Under a DSCR Mortgage structure, the lender calculates net operating income for the subject property — total rental receipts minus operating expenses — and divides that figure by the annual debt service on the proposed loan. A borrower whose personal income would not satisfy a conventional debt-to-income test can still qualify if the property's projected rents produce a DSCR at or above the lender's threshold, typically set at 1.0 to 1.25.
This approach shifts underwriting risk from the borrower's balance sheet to the property's income potential. Lenders relying on DSCR analysis must therefore assess local rental market conditions, vacancy rates and operating cost assumptions with particular rigour, since those inputs drive the ratio that determines approval.
The distressed-area context
Distressed communities in the United States carry a legacy of restricted credit access. Federal redlining maps from the 1930s explicitly labelled neighbourhoods as high-risk lending zones, a designation that shaped decades of bank behaviour and contributed to the disinvestment that defines many of these areas today. The result is a persistent gap between capital availability and community need.
Policy has attempted to address this gap through several channels. The Community Development Financial Institutions Fund — the CDFI Fund — plays a role in generating economic growth in underserved markets by certifying mission-driven organisations and injecting new sources of capital into communities that conventional finance has bypassed, according to the fund's own description of its mandate.
115-97, offer tax incentives designed to attract private investment into designated low-income census tracts; the Joint Committee on Taxation published an analysis of 2019–2021 tax return data related to investments in those zones in October 2023. Federal Reserve research has also examined whether community development financing produces measurable revitalisation or stabilisation effects in targeted areas.
The DSCR Mortgage operates alongside — rather than as a replacement for — these policy instruments.
How did markets react?
The broader US Real Estate investment environment in which DSCR lending is expanding is under significant pressure. Investor sentiment in the single-family housing market deteriorated sharply through mid-2026: fully 45% of respondents to the RCN Capital/CJ Patrick Company Investor Sentiment Index survey published on 14 August 2026 said market conditions had worsened, the highest share in the survey's history.
The US 30-year mortgage rate reached a recent low at the end of February 2026 before rising sharply after the start of the war with Iran; by August 2026 it stood at its highest level in over a year, according to the same survey data. That rate environment compresses margins for leveraged real estate investors across all product types, including DSCR borrowers, whose debt service calculations are directly sensitive to prevailing rates.
Despite the headwinds, the DSCR structure retains a structural advantage in distressed markets: because approval hinges on rental yield relative to debt cost rather than on the borrower's personal income, rising rates affect the arithmetic of the deal but do not disqualify the borrower outright — provided projected rents adjust accordingly.
Why it matters
The DSCR Mortgage represents a meaningful shift in who can participate in US Real Estate investment in areas that conventional underwriting has historically excluded. By anchoring eligibility to property-level cash flow, the product opens a path for smaller investors — individuals who own rental properties but whose personal income statements would not satisfy standard mortgage criteria — to access financing in markets where yields can be higher precisely because prices have been depressed by decades of disinvestment.
For distressed communities, the implications extend beyond individual transactions. Renovation activity financed by DSCR loans can stabilise housing stock, raise assessed values and generate local employment, effects that community development research has sought to quantify. The CFPB and federal banking regulators, including those overseeing the Community Reinvestment Act framework, have established criteria under which loans and investments that support community development in low- and moderate-income areas receive regulatory credit — a structure that can align bank incentives with DSCR lending activity in qualifying geographies.
- DSCR threshold: net operating income divided by total debt service; lender minimums typically range from 1.0 to 1.25.
- Investor sentiment: 45% of surveyed single-family housing investors said conditions worsened as of August 2026 — the highest share on record.
- Rate environment: the US 30-year mortgage rate at its highest in over a year as of August 2026, following a sharp post-February rise.
Risks remain. If projected rents do not materialise, a DSCR loan that appeared sound at origination can deteriorate rapidly, with consequences for both the borrower and, in aggregate, for the lenders and securitisation vehicles that hold these assets. Federal Reserve and FDIC research on commercial mortgage underwriting has documented how risk perception shapes loan terms in securitised pools — a dynamic that applies equally to DSCR residential products as they scale.
What to watch next
- US 30-year mortgage rate trajectory: any further movement in rates will directly alter the DSCR arithmetic for new originations and affect the pipeline of distressed-area deals.
- CFPB regulatory posture: the Consumer Financial Protection Bureau's approach to non-QM lending products, including DSCR mortgages, will shape disclosure requirements and lender compliance costs.
- CDFI Fund programme cycles: upcoming application windows for CDFI certification and capital injection programmes will determine how much institutional capacity is available to co-invest alongside DSCR lenders in qualifying communities.
Sources:wsj.comcnbc.comcdfifund.govocc.treas.govjct.govfederalreserve.govfederalreserve.govfdic.gov
UCapital Asset Management LLP or group companies may have commercial relationships with the companies mentioned. This content is not financial advice.
Sign up for free to ask the AI about this article.
Multiples, financials, sentiment and risks in 60 seconds, with live data.