
CoreWeave's $35 Billion Debt Pile Exposes Residual-Value Risk in AI GPU Lending
Over $20 billion in GPU-backed loans rest on collateral that depreciates every quarter. CoreWeave's negative cash flow and mounting interest burden are putting AI credit markets under scrutiny.
- 01GPU-backed loans across the AI infrastructure sector exceed $20 billion, secured by collateral whose market value erodes each quarter.
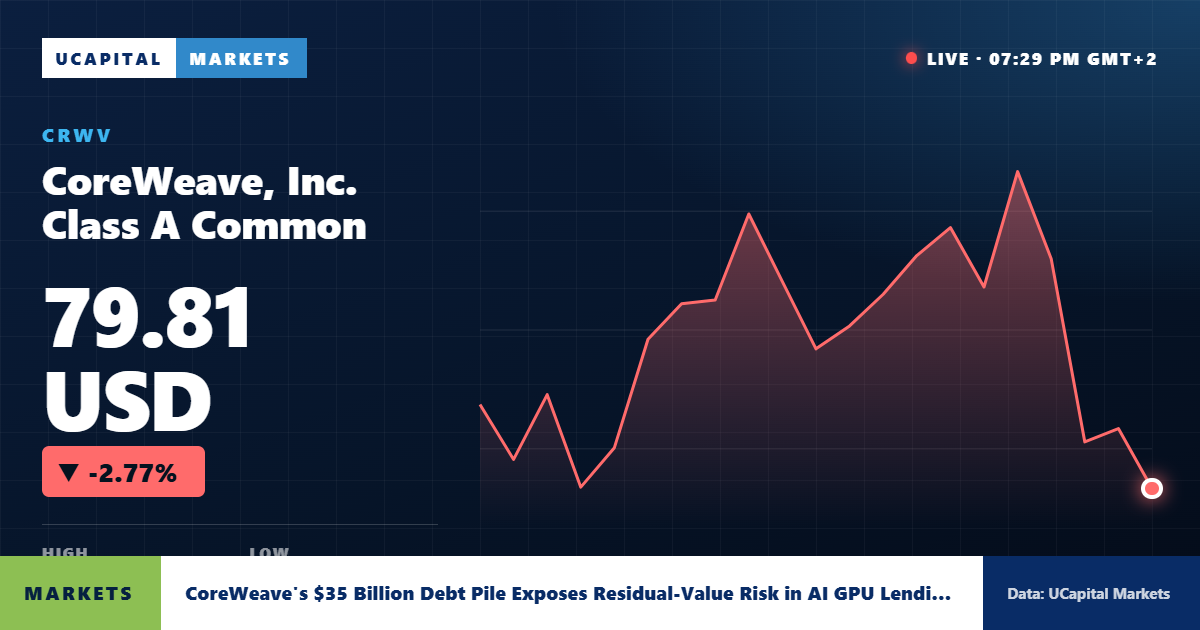
- 02CoreWeave (CRWV) carries approximately $35 billion in debt, with prospective annual interest costs of roughly $3 billion, while remaining cash-flow negative.
- 03CoreWeave's accumulated deficit stood at $2.2 billion as of its latest reported quarter, even as revenue reached $2.58 billion in the most recent period.
- 04CoreWeave completed its IPO in March 2025, issuing 36,590,000 Class A shares at $40.00 per share, and has since filed multiple 8-K disclosures through September 2026.
More than $20 billion in GPU-backed loans underpinning the United States AI infrastructure boom are secured by Nvidia H100 accelerators and similar hardware whose resale value shrinks materially with every passing quarter — a structural mismatch that is drawing fresh scrutiny from credit analysts and regulators alike. CoreWeave, Inc. (CRWV), the largest pure-play AI cloud provider in the country, sits at the centre of the debate, carrying roughly $35 billion in total debt and prospective annual interest costs of approximately $3 billion while still generating negative free cash flow.
The concern is not merely about one company.
What happened
CoreWeave has accumulated a debt load of approximately $35 billion, financed in large part through GPU-backed credit facilities that use its fleet of Nvidia H100 and related accelerators as collateral. The company entered into its first Delayed Draw Term Loan facility in July 2023, a structure that has since been amended and expanded, according to its Form 424B3 filing.
Net cash used in investing activities reached approximately $10.3 billion for the year ended December 31, 2025, reflecting the scale of hardware procurement required to sustain its cloud business, as disclosed in the company's annual report.
On the revenue side, CoreWeave reported $2.58 billion in revenue for its latest quarter, beating the consensus estimate of $2.55 billion, and posted an earnings-per-share loss of $1.03 against an estimate of $1.21. Despite the revenue beat, the company's accumulated deficit stood at $2.2 billion as of the same period, and its own filings acknowledge that future investments "may require significant debt and/or equity financing." The company completed its initial public offering in March 2025, selling 36,590,000 Class A shares at $40.00 per share.
What is residual-value risk in AI GPU lending?
Residual-value risk refers to the danger that the collateral backing a loan — in this case, AI accelerators such as the Nvidia H100 — is worth significantly less at loan maturity than lenders assumed when the credit was extended. GPU-backed lending structures typically assign a forward value to the hardware fleet; if that value proves optimistic, the loan-to-value ratio deteriorates, potentially leaving lenders under-collateralised.
AI accelerators depreciate rapidly for two compounding reasons: technological obsolescence and supply normalisation. Each successive generation of Nvidia chips — the H100 has already been followed by newer architectures — reduces the relative performance premium of older hardware, compressing secondary-market prices. At the same time, as Nvidia (NVDA) scales production and hyperscalers build their own silicon, the scarcity premium that inflated H100 valuations in 2023 and 2024 fades. Lenders who booked collateral at peak-cycle prices face the steepest mark-to-market exposure.
- $20 billion+ — estimated GPU-backed loans outstanding across the AI infrastructure sector in the United States.
- $35 billion — CoreWeave's approximate total debt as of the latest available disclosures.
- ~$3 billion — CoreWeave's prospective annual interest expense at current debt levels.
- $10.3 billion — net cash used in CoreWeave's investing activities for the year ended December 31, 2025.
- $2.2 billion — CoreWeave's accumulated deficit as of its latest reported quarter.
Why it matters
The systemic dimension of GPU-backed lending extends well beyond CoreWeave's own balance sheet. When a single borrower accounts for a significant share of a novel asset class, its financial health becomes a bellwether for the entire credit structure. If CoreWeave were to face refinancing stress — whether from a deterioration in GPU collateral values, a slowdown in AI cloud demand, or a rise in funding costs — the repricing of GPU-backed debt across the sector could be abrupt and disorderly.
For the broader AI infrastructure market, the stakes are high. Lenders who extended GPU-backed credit during the 2023–2024 demand surge priced collateral at a moment of acute scarcity. A normalisation of Nvidia H100 secondary-market values, accelerated by newer chip generations, would mechanically widen the gap between outstanding loan balances and recoverable collateral — a dynamic that credit markets have not yet been forced to price in a downturn scenario.
Nvidia (NVDA), whose hardware underpins the entire collateral pool, reported revenue of $96.22 billion in its latest quarter — beating the $92.27 billion estimate — with a trailing price-to-earnings ratio of 28.84 and a forward P/E of 24.61. Nvidia's continued dominance in AI accelerator supply means that each new product cycle it introduces has the potential to accelerate the depreciation of the H100 fleet that serves as collateral for tens of billions of dollars in outstanding loans.
How is CoreWeave's cash flow holding up?
CoreWeave generated $3.058 billion in net cash from operating activities for the year ended December 31, 2025, up from $2.749 billion in 2024 and $1.833 billion in 2023, according to its annual report. The operating cash flow trajectory is positive, but it is dwarfed by the investing outflows required to maintain and expand the GPU fleet, leaving free cash flow deeply negative. With approximately $3 billion in prospective annual interest costs, the company's ability to service its debt depends heavily on sustaining — and growing — its revenue base.
That dual message — adequate liquidity today, uncertain tomorrow — is characteristic of capital-intensive infrastructure businesses at an early stage of their debt cycle.
What to watch next
Several catalysts in the coming quarters will determine whether residual-value risk in AI GPU lending remains a theoretical concern or crystallises into a credit event.
- CoreWeave's next quarterly earnings — revenue growth, operating cash flow and any update to debt facilities will be the primary indicators of whether the company's debt-service capacity is improving.
- Nvidia's next product cycle — the launch of successor architectures to the H100 will set the pace of collateral depreciation across the entire GPU-backed loan market.
- Secondary-market GPU pricing — spot and forward prices for H100 units in the secondary market serve as the most direct real-time signal of collateral value erosion.
- Regulatory scrutiny of AI credit structures — U.S. banking regulators have begun examining concentrated exposures to novel asset classes; any formal guidance on GPU collateral valuation would reshape lending standards across the sector.
- CoreWeave's refinancing calendar — the maturity profile of its Delayed Draw Term Loan facilities and any covenant tests tied to collateral coverage ratios will be closely watched by credit markets.
The central question for investors and lenders alike remains unanswered: in a market where the hardware underlying $20 billion in loans depreciates faster than the loans amortise, who absorbs the difference — and when does the market begin to price that risk explicitly?
Sources:UCapital Markets (ucapital.com)UCapital Markets (ucapital.com)sec.govsec.govsec.govsec.govsec.gov
UCapital Asset Management LLP or group companies may have commercial relationships with the companies mentioned. This content is not financial advice.
Sign up for free to ask the AI about this article.
Multiples, financials, sentiment and risks in 60 seconds, with live data.