
Iran Conflict Puts the TACO Pattern's Equity Calm to Its Hardest Test Yet
Brent crude above $104 a barrel, tanker attacks in the Strait of Hormuz and a rising geopolitical risk premium are straining the market resilience that survived every earlier Trump-era shock.
- 01Brent crude traded above $104 a barrel on 8 October 2026, with earlier sessions seeing the benchmark near $101–$102 amid Gulf shipping attacks.
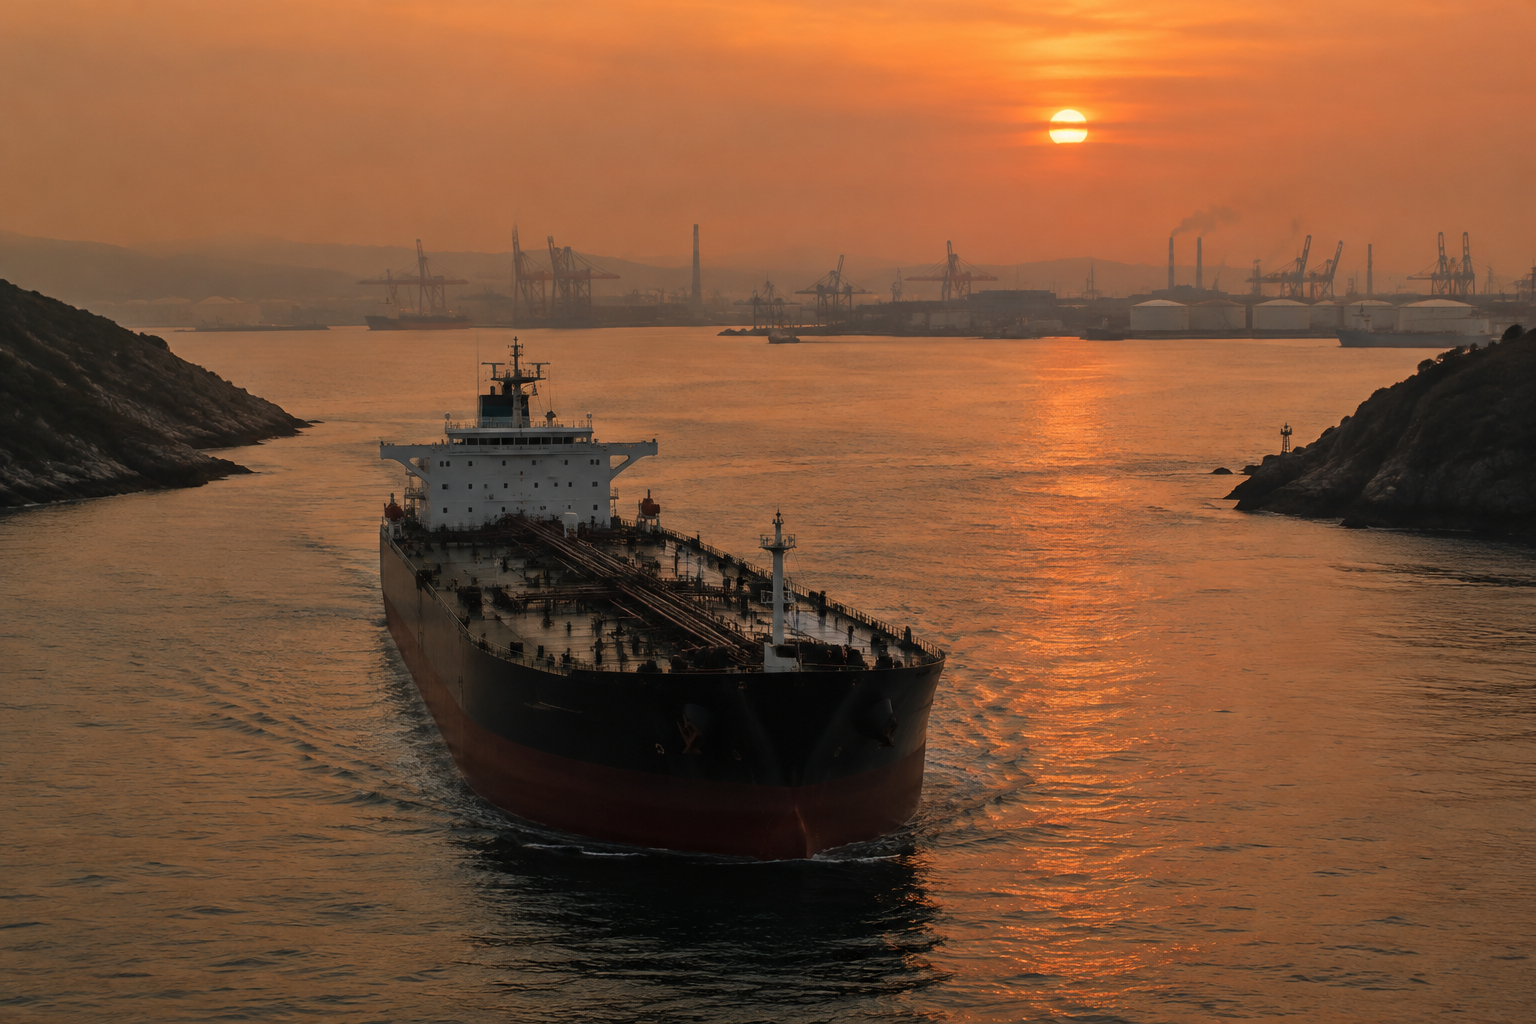
- 02Attacks on tankers in the Gulf and the Strait of Hormuz have intensified supply concerns, prompting discussion of emergency stock releases.
- 03The so-called TACO pattern — markets shrugging off Trump-era geopolitical shocks — faces its most severe stress test as the Israel-Iran air war enters its sixth day.
- 04The Indian rupee fell to 96.65 against the US dollar on 8 October as foreign institutional investors offloaded equities under pressure from high crude prices.
Brent crude traded above $104 a barrel on 8 October 2026 as the Israel-Iran air war raged into its sixth day, tanker attacks multiplied across the Gulf and the Strait of Hormuz, and equity markets confronted a geopolitical risk premium that earlier Trump-era crises never managed to sustain.
The episode is shaping up as the most consequential test of the so-called TACO pattern — the market habit of treating each geopolitical shock as temporary and fading it back to calm — because, unlike previous episodes, the supply disruption is physical, the price level is triple-digit and the conflict shows no sign of a quick diplomatic off-ramp.
What happened
Brent crude climbed to $101.53 a barrel in early Asian trading on 8 October as attacks on tankers in the Gulf and the Strait of Hormuz intensified, before extending gains to above $104 later in the session. West Texas Intermediate (WTI) tracked the move higher. The surge came as U.S. President Donald Trump cut short his G7 trip and returned to the White House, with the Israel-Iran air war in its sixth day.
Plans to release emergency oil stocks were under discussion, but the announcements did little to cap prices, reflecting how deeply traders are pricing in the risk of a prolonged supply shock. Bond markets also moved: yields rose alongside crude, a combination that compresses the cushion equity valuations depend on.
What is the TACO pattern — and why is it under pressure?
The TACO pattern describes the repeated tendency of financial markets to absorb Trump-era geopolitical shocks — tariff announcements, diplomatic confrontations, military escalations — and recover quickly, as if each event were a one-off. The pattern held through multiple earlier episodes, reinforcing a reflexive calm among equity investors each time a new headline broke.
The Iran conflict is different in at least three structural ways. First, the price of crude is already above $100, a level that historically feeds into corporate cost structures and consumer spending with a lag that equity multiples rarely price in immediately.
Second, the supply disruption is not a threat but an active one: tanker attacks in the Strait of Hormuz — through which a significant share of global seaborne oil passes — are ongoing. Third, the conflict has drawn in state actors in a way that makes a rapid de-escalation harder to engineer than a tariff rollback or a diplomatic tweet.
How did markets react?
The S&P 500 (INDEX:SP500) faced a complex backdrop on 8 October, with oil's gains historically producing mixed equity outcomes. On days when crude has risen 3% or more, the S&P 500's performance has been more nuanced than a simple inverse relationship would suggest — a pattern that complicates the narrative of oil as a straightforward headwind for stocks.
The CBOE Volatility Index (VIX) reflected the uncertainty, with bond markets adding to the pressure as yields fell — or in some sessions rose — in response to the dual pull of a risk-off flight to safety and the inflationary signal embedded in triple-digit crude. The geopolitical risk premium, long suppressed by the TACO reflex, is now a live variable in asset pricing rather than a footnote.
- Brent crude above $104 a barrel on 8 October 2026
- Earlier session: Brent at $101.53, driven by Gulf and Strait of Hormuz tanker attacks
- Indian rupee at 96.65 per US dollar on 8 October, pressured by high crude and foreign institutional equity outflows
- Emergency oil stock releases discussed but insufficient to cap prices
- Israel-Iran air war in its sixth day as of 8 October
Why it matters
A sustained crude price above $100 is not merely a headline number. It feeds through to airline costs, petrochemical margins, freight rates and, ultimately, consumer prices — each channel capable of eroding the earnings growth that has underpinned equity valuations through the Trump era. The longer crude stays elevated, the harder it becomes for the TACO reflex to reassert itself, because the damage accumulates in quarterly income statements rather than evaporating with a ceasefire announcement.
Emerging-market economies with large oil import bills are already feeling the strain. The Reserve Bank of India intervened on 8 October to stabilise the rupee after foreign institutional investors offloaded equities, pushing the currency to 96.65 against the US dollar — a move that illustrates how energy-price shocks transmit rapidly into currency and capital-flow dynamics well beyond the immediate conflict zone.
For energy markets broadly, the Strait of Hormuz attacks represent a qualitative shift. Previous geopolitical risk premia in oil were largely anticipatory; this one is being validated in real time by disrupted shipping lanes. Emergency stock releases, while a standard policy tool, address the symptom rather than the cause, and their effectiveness diminishes the longer the conflict persists.
Risks and counterpoints
Not every analyst is convinced the TACO pattern is broken. The pattern's durability rested on the observation that markets consistently overestimated the permanence of Trump-era shocks, and a ceasefire or back-channel diplomatic agreement could reassert that logic quickly. Emergency oil releases, if coordinated among major consumer nations, could also compress the risk premium faster than current price action implies.
There is also the question of demand. A sustained period of triple-digit crude tends to destroy its own demand base, particularly in price-sensitive emerging markets, which can eventually cap the upside in energy prices without a supply-side resolution. That self-correcting mechanism, however, operates over quarters, not days — and equity markets are pricing the near term.
The bond market's behaviour adds another layer of ambiguity. Rising yields alongside rising crude create a stagflationary signal that central banks find difficult to respond to cleanly: tightening to contain inflation risks amplifying the growth slowdown that high energy prices are already engineering.
What to watch next
- Strait of Hormuz shipping data: Any escalation or de-escalation in tanker attacks will be the most immediate price signal for Brent crude and WTI.
- Emergency oil stock coordination: Whether major consumer nations announce a coordinated release — and its scale — will determine how much of the risk premium can be administratively compressed.
- Israel-Iran diplomatic channels: With Trump back at the White House after cutting short the G7, any signal of back-channel engagement or a ceasefire framework would be the clearest catalyst for a reversal in the geopolitical risk premium.
- S&P 500 earnings season: Corporate guidance on energy costs and margin pressure will be the first hard data point on how much of the crude shock is passing through to earnings — a key input for whether equity calm can be sustained.
- VIX trajectory: A sustained move higher in the CBOE Volatility Index would signal that the TACO pattern's suppression of volatility is giving way to a more durable repricing of geopolitical risk.
Sources:wsj.comreuters.comeconomictimes.indiatimes.combusiness-standard.commarketwatch.com
UCapital Asset Management LLP or group companies may have commercial relationships with the companies mentioned. This content is not financial advice.
Sign up for free to ask the AI about this article.
Multiples, financials, sentiment and risks in 60 seconds, with live data.